Self Storage Occupancy May Be Hiding Misaligned Street Rates
High occupancy can be a very polite liar.
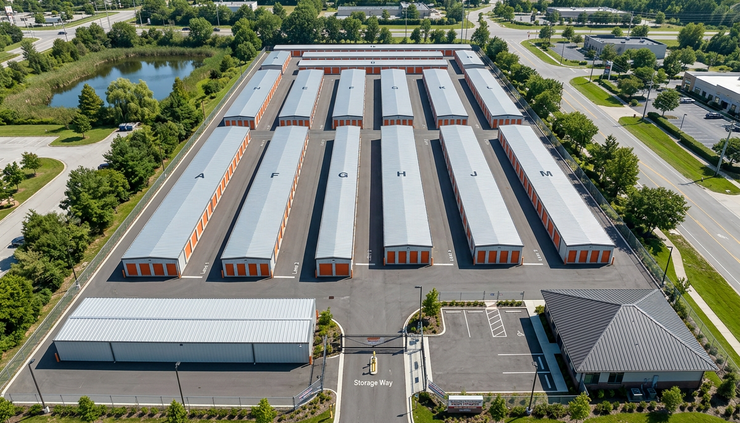
A facility may look healthy at 94% occupied. The rent roll is full. Existing customers are paying. The dashboard is mostly green. Nobody is running through the building with a clipboard and a fire extinguisher.
But the next rental is still the market’s vote.
If new customers stop taking the remaining units, strong self storage occupancy can hide a pricing problem for weeks or months. The issue is not the occupied space. Those customers made their decisions in the past. The question is whether today’s prospects still accept today’s street rates.
Occupancy shows what happened before, not what the next renter will do
Occupancy is a stock metric. It tells how much inventory is currently rented.
That matters. A lot. Occupancy drives cash flow, operating leverage, and asset value. Boards and lenders care about it for good reason.
But occupancy is not the same as current demand.
A customer who rented a 10x10 unit nine months ago at one rate does not prove a new customer will rent the same size today at the current rate. The market may have changed. Competitors may have repositioned. Promotions may have returned. Demand may have softened in that unit type. Search behavior may have shifted. The local move cycle may have cooled.
Occupied inventory is history with a lock on the door.
Available inventory is the real exam.
That distinction matters most when a facility has only a few units left in a size. A 94%-occupied store can feel bulletproof, while the remaining units quietly collect dust like gym equipment in February. If the open inventory is concentrated in one or two sizes, the facility may have a very specific pricing issue hidden inside a very attractive occupancy number.
This is where rental velocity enters the picture. If available 10x10s are sitting longer, quote activity is slowing, and achieved move-in rates are below the posted rate, the market is sending a signal. It may be faint. It may be annoying. It may arrive wearing Crocs. But it is still a signal.
A 94% occupied facility can still be out of step
Take a hypothetical facility with 94% occupancy.
The property has performed well for years. It has strong drive-up exposure, stable reviews, and clean operations. Its rent roll looks solid. The team has held 10x10 street rates near the top of the trade area because occupancy has stayed high.
Now the last few 10x10 units are available.
Over the past several weeks, they have produced few rentals. Web traffic has not vanished, but conversion has weakened. Phone leads ask about price more often. A few prospects reserve, then fail to move in. Achieved move-in rates are lower than the posted rate because discounts or manual concessions help close the few deals that do happen.
At the same time, comparable competitors have gradually repositioned.
They did not slash rates overnight. They adjusted in small steps. Some lowered web rates. Some added “first month” promotions. Some created online-only offers. A few shifted pricing on 10x10s while holding larger units steady. Their moves are not dramatic enough to create panic, but the gap has widened.
This is the dangerous part.
The facility’s occupancy still says, “Relax.”
The rental velocity says, “Maybe do not relax so aggressively.”
The gap between those two messages is where revenue management earns its keep.
A full property can support rate confidence. It can also delay recognition. The same high occupancy that protects revenue today can make a team slower to see that new-customer pricing has drifted away from current willingness to rent.
That point is easy to miss because the P&L does not scream right away. Existing tenant rent is still coming in. Vacates may be normal. The store manager may still feel busy. The problem starts at the margin, with the next rental.
And in self storage pricing, the margin is where tomorrow’s trend begins.
Competitor pricing gives context, not the answer
Competitor rates matter. Ignoring them is like playing poker with your eyes closed. Bold choice. Bad quarter.
But competitor pricing alone does not answer whether action is needed.
A lower competitor rate may not be comparable. That facility may have weaker access, older doors, poor visibility, limited security features, or a less convenient location. Its posted price may require autopay, insurance, an admin fee, or a promotion that disappears after a short period. The unit could be upstairs, interior, or less desirable. The website may show teaser inventory that is barely available.
The reverse can also be true. A facility may believe its premium is justified, but the customer may not agree. If prospects see similar distance, similar unit type, similar move-in process, and a lower effective price elsewhere, the story gets simple. The other operator wins the rental. No committee needed.
Competitor data needs interpretation.
Good market intelligence should separate noise from meaningful movement. Look for patterns such as:
Comparable facilities changing the same size category over time
Promotions appearing more often, or staying active longer
Rate gaps widening between your available units and nearby alternatives
Competitors holding rates on other sizes while moving only the size you are struggling to rent
Web rates and phone quotes pointing in the same general direction
Inventory availability changing across the trade area
A single competitor dropping a rate is not a commandment from Mount Revenue. It is one data point. A pattern across comparable properties is more useful.
The same applies to internal data. One slow week does not prove mispricing. Seasonality, weather, local move patterns, student cycles, and temporary inventory mix can all distort results. But weak conversion, slower rentals, more concessions, and rising availability in the same size deserve attention.
Neither occupancy nor competitor pricing can carry the whole argument alone.
Occupancy tells what is already rented. Competitor pricing tells what alternatives appear to cost. The decision lives in the connection between available inventory, customer response, achieved rents, and market movement.
The best evidence comes from the path to move-in
A facility does not need a magic threshold to spot pressure. It needs a clear view of the path from exposure to rental.
That path usually includes:
Signal | What it helps reveal |
Available inventory by size | Whether the issue is broad or concentrated |
Rental velocity | How quickly current units convert into rentals |
Achieved move-in rate | What rate customers actually accept after concessions |
Lead and reservation conversion | Whether interest is turning into paid rentals |
Vacates | Whether occupancy protection is weakening from the back door |
Competitor rates and promotions | Whether the market has repositioned around the facility |
Inquiry notes and objections | Whether price resistance is rising in real conversations |
The value is not in one metric. The value is in the pattern.
For example, available 10x10 inventory may rise while lead flow remains decent. That points to conversion, not awareness. If competitors have also lowered effective prices, pricing may be part of the answer.
Or, lead flow may drop across all unit types while competitor pricing is stable. That may point to seasonality, search visibility, local demand, or operational response time. Lowering rates blindly would be like fixing a flat tire by repainting the car.
Vacates also deserve a seat at the table.
If move-outs rise while move-ins slow, high occupancy can unwind faster than expected. The property may still look fine today, but the replacement engine is coughing. Existing tenants can carry the store for only so long if new demand does not refill the funnel.
Achieved move-in rate is especially useful. Published street rates are the shelf price. Achieved rate is the register receipt. If the team posts one rate but consistently rents at another through discounts, exceptions, or promotional stacking, the actual market-clearing price may already be lower than the official rate.
That hidden gap matters for revenue management because it affects both forecasting and credibility. A system that treats posted rates as reality while field behavior tells another story will misread demand.
Scenario comparison beats reflexive rate moves
The answer is not “drop rates whenever rentals slow.” That is how operators train customers to wait for discounts. It is also how margin goes missing, usually without leaving a forwarding address.
The answer is structured comparison.
A revenue team can compare scenarios without locking itself into rigid formulas. The point is to understand trade-offs before making a change.
One scenario may hold current street rates and watch whether limited inventory rents through. Another may test a targeted offer on the affected unit size. Another may narrow the rate gap against the most comparable competitors while protecting rates in stronger sizes. Another may keep price steady but change promotion visibility, reservation follow-up, or channel mix.
Each scenario should be judged against the same business questions:
What inventory is actually at risk?
How many rentals are needed to maintain the desired occupancy path?
What rate are customers actually accepting?
What happens if vacates continue at the recent pace?
How far has the competitor set moved, and who is truly comparable?
Does the issue show up in one size, one channel, or the whole store?
What revenue is protected by holding rate, and what occupancy is risked by waiting?
This is where executives should resist clean but shallow answers.
“Occupancy is 94%, so rates are fine” is too simple.
“Competitors are lower, so we must match” is also too simple.
Both can be wrong at the same time, which is rude, but common.
The better question is whether the current rate supports the next set of rentals needed for the asset plan. That requires looking at occupied inventory and current willingness to rent as separate concepts.
A facility with strong occupancy may have earned the right to hold rate. It may also be carrying stale street rates that no longer match demand. The difference shows up in velocity, conversion, achieved rents, and inventory position before it shows up in the headline occupancy number.
FAQ
What is the risk of relying too much on occupancy?
Occupancy can lag the market. It reflects past rentals and current tenants, not whether new customers will accept today’s price. A facility can stay highly occupied while the remaining units become harder to rent.
Should operators match lower competitor street rates?
Not automatically. Competitor pricing needs context. Unit type, location, access, promotion terms, fees, availability, and property quality all affect comparability. Matching the wrong competitor can give away revenue without solving the real problem.
Which metric best shows whether pricing is misaligned?
No single metric answers it. Rental velocity, available inventory, achieved move-in rates, conversion, competitor activity, promotions, and vacates work best together. The pattern matters more than any one number.
Can strong occupancy justify premium pricing?
Yes, when current demand supports it. Strong occupancy can justify rate confidence, but only if available units still rent at acceptable speed and achieved rates remain close to the intended price position.
How should teams compare pricing scenarios?
Start with the affected inventory and the business objective. Then compare likely outcomes for rent, move-ins, vacancy exposure, and market position. Avoid one-size-fits-all thresholds. Use evidence from the property and the trade area.
The takeaway is to separate comfort from evidence
High occupancy feels good. It should. Full buildings pay bills.
But comfort is not evidence that current rates still meet demand. The market votes through move-ins, conversions, accepted rents, and competitor alternatives. The rent roll tells one part of the story. The remaining inventory tells another.
When those stories conflict, do not let the prettier one win by default.
A.R.M.S. Revenue Intelligence is built around that connection: pricing, availability, demand signals, competitor movement, and market intelligence working together instead of living in separate tabs. For teams managing self storage pricing across changing markets, that connected view helps separate real strength from hidden friction.


Comments